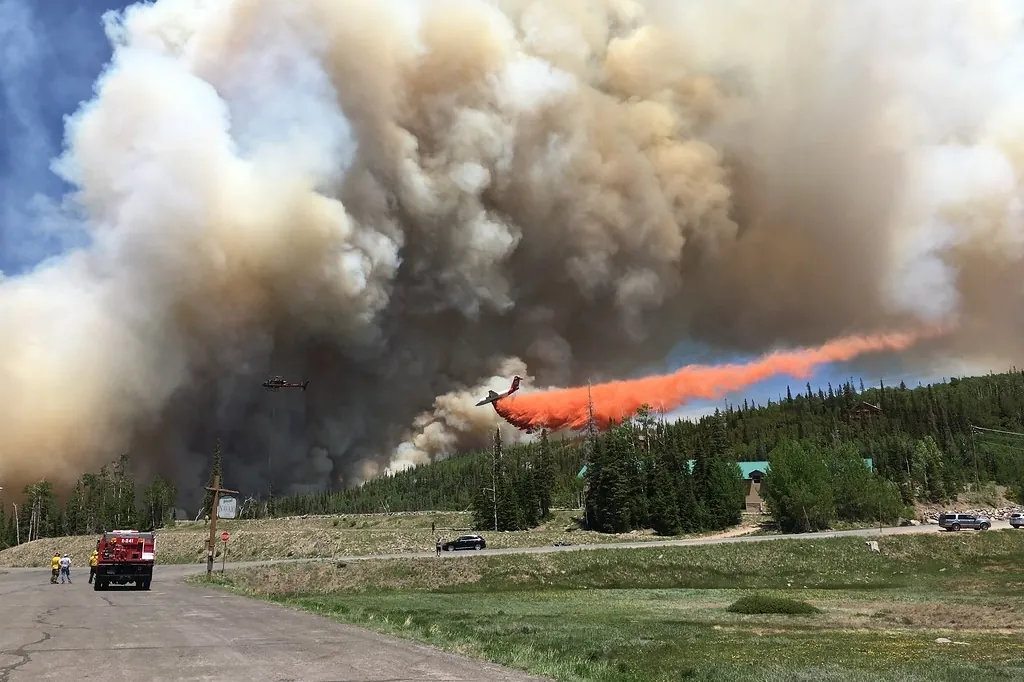
Utah’s wildland-urban interface
Utah’s growth has pushed homes into the foothills of the Wasatch and Oquirrh mountains, the canyons of Summit and Wasatch counties and the juniper country of southern Utah. The 2017 Brian Head Fire burned homes and cabins in Iron and Garfield counties. In 2018, the Pole Creek and Bald Mountain fires forced large evacuations in south Utah County. Each fire season brings new starts.
Two very different wildfire claims
- Total and major losses. These involve policy limits, extended replacement cost, debris removal, code upgrades and additional living expenses. The challenge is making sure the rebuild estimate reflects today’s construction costs.
- Smoke and ash. Homes that didn’t burn can still have smoke in HVAC systems, insulation and soft goods, plus ash on roofs and in landscaping. These claims are frequently underpaid because the damage isn’t obvious.
What we document
Ash and char deposits, soot on surfaces, filtration and HVAC contamination, heat damage to windows, siding and vinyl, and damage to fences, sheds, decks and landscaping. Testing by an environmental professional can support cleaning and replacement scope.
Frequently asked questions
My house didn’t burn but smells like smoke. Is that a claim?
It may be. Smoke infiltration can be covered physical damage under many policies. Document it early and consider professional testing.
Is landscaping covered after a wildfire?
Many policies cover trees, shrubs and plants with a limit per plant and an overall cap. Check the ‘trees, shrubs and other plants’ provision.
How long do I have to rebuild?
Policies set time limits to recover replacement cost. Some states extend them after declared disasters. Confirm the deadline for your policy in writing.