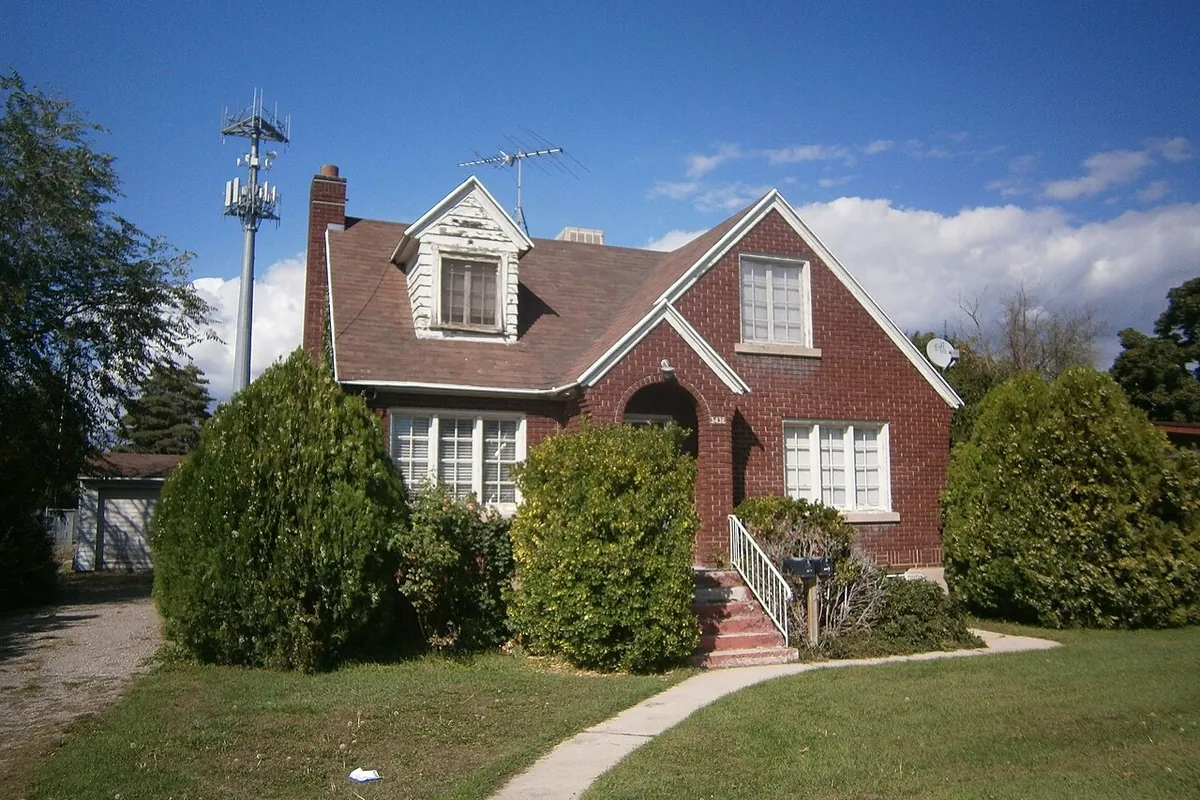
Earthquake risk along the Wasatch Front
On March 18, 2020, a magnitude 5.7 earthquake centered near Magna shook the Salt Lake Valley. Chimneys toppled, brick parapets failed and many older homes cracked. Geologists consider a larger Wasatch Fault earthquake a long-term possibility, and much of Utah’s older brick housing is vulnerable.
Coverage comes first
Standard homeowners policies typically exclude earth movement. Earthquake coverage is usually added by endorsement or purchased as a separate policy, often with a deductible of 10% or more of the dwelling limit. Appraisal only helps when coverage applies and the dispute is about the amount.
What earthquake valuations need
- Careful documentation separating new earthquake cracking from older settling.
- Masonry and chimney repair or rebuild, including bracing and code requirements.
- Foundation evaluation, sometimes with an engineer’s report.
- Interior drywall and plaster cracking throughout the home, not only in the worst rooms.
- Pricing that accounts for limited contractor availability after a regional event.
Frequently asked questions
Does homeowners insurance cover earthquakes in Utah?
Usually not without an endorsement or separate policy. Check your declarations page for earthquake coverage and its deductible.
How do I prove cracks are from the earthquake?
Before-and-after photos, inspection records and an engineer’s evaluation are the strongest evidence. Fresh, clean crack edges and patterns consistent with shaking also help.
Is it worth appraising if I’m near my deductible?
Sometimes. If the disputed amount pushes the loss well above the deductible, it can make a real difference. If not, appraisal costs may outweigh the benefit.